Accounts receivable automation can remove repetitive work, but a faster workflow is not necessarily a better-controlled one. Retail finance leaders must preserve approval authority, reliable customer records, audit trails, and human judgment while improving payment visibility and collection speed.
Peak Design’s move away from manual AR offers a useful starting point. However, the Retail Dive article describing it is sponsored content rather than independent evidence. Any vendor-reported benefits should therefore be treated as claims to validate—not guaranteed results. The practical lesson is to automate defined activities around invoicing and collections while designing explicit controls for exceptions, overrides, and customer disputes.
Start with the operational problem, not the software
The sponsored case presents Peak Design’s finance team as constrained by manual AR work and seeking better efficiency and visibility. It describes a move toward automation intended to reduce repetitive activity and give staff more capacity for higher-value work. That direction is plausible, but the case should not be read as proof that the same platform or configuration will deliver equivalent results for another retailer.
Before selecting technology, map one invoice from creation to settlement. Record who generates it, what source data they use, how it reaches the customer, when reminders begin, how payments are matched, and where disputes are recorded. Include variations for wholesale accounts, distributors, marketplaces, franchisees, and other customer types relevant to the business.
Look for bottlenecks such as invoices waiting for supporting documents, staff switching between systems to confirm payment status, inconsistent reminder timing, cash posted without a clear invoice match, and disputes held in personal inboxes. Separate genuine control steps from habits created because systems do not exchange data. A second approval for an unusual credit note may be necessary; manually copying every invoice number into another application probably is not.
Choose tasks by risk and repeatability
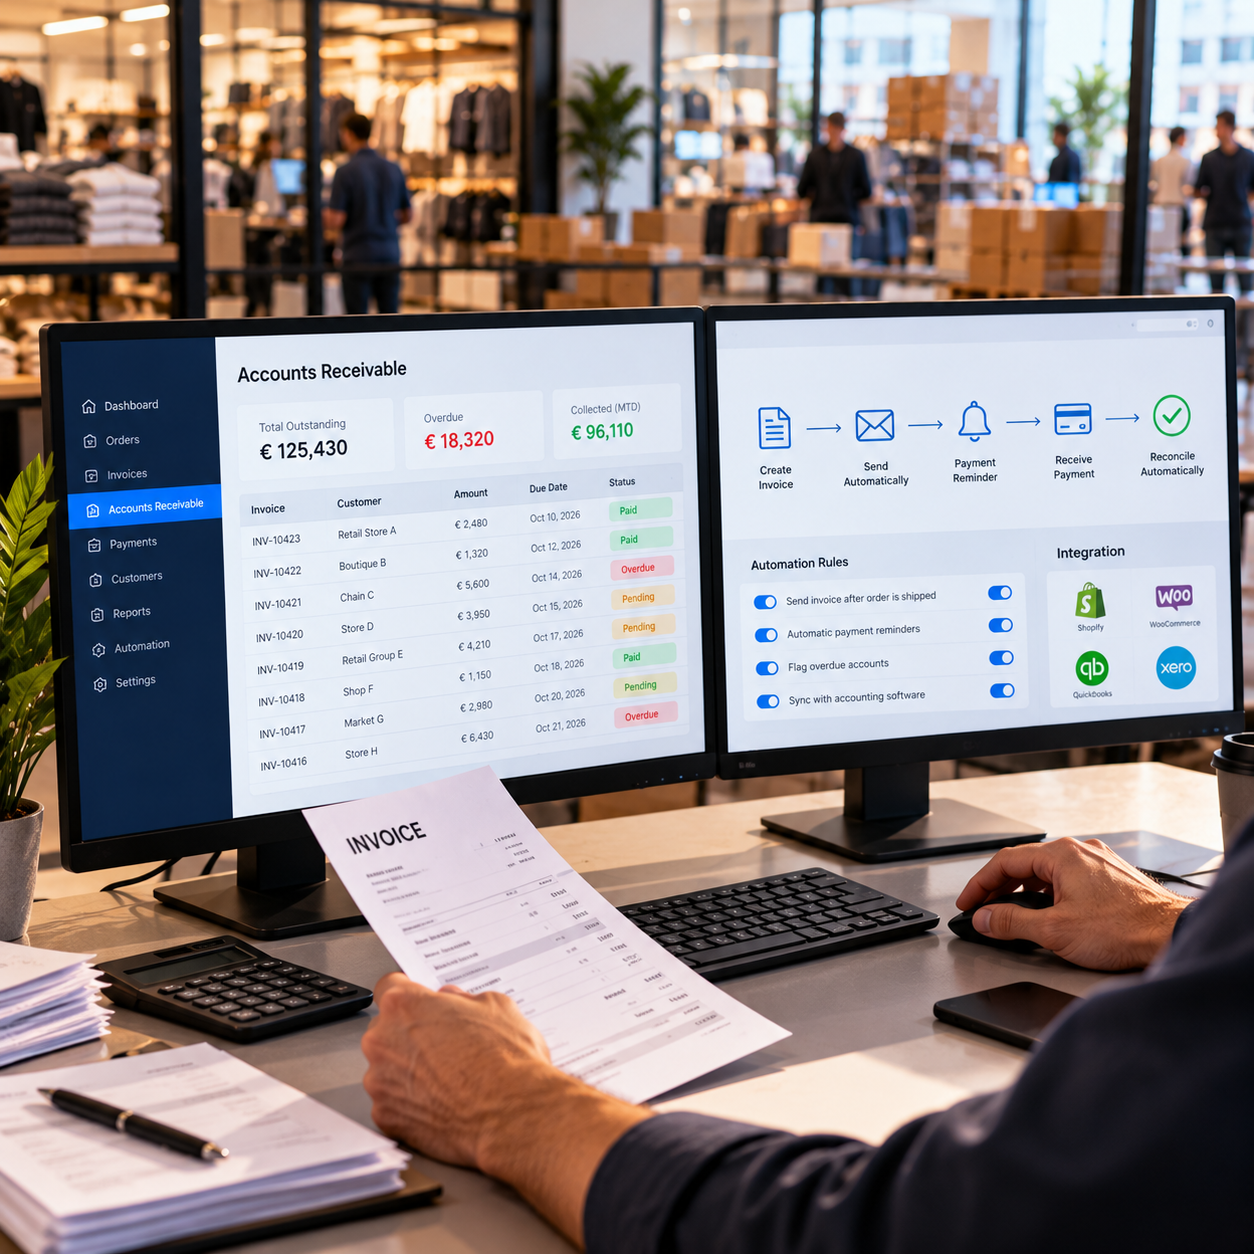
The best initial candidates are high-volume, rules-based tasks with predictable inputs. These may include generating invoices from approved transaction data, scheduling delivery, issuing reminders according to customer terms, presenting payment options, importing bank information, suggesting payment matches, and routing overdue accounts into collection queues.
Automation should redesign responsibilities rather than merely reproduce every manual click. For example, software can propose a match between a receipt and several invoices, while a finance employee approves uncertain allocations. It can send a standard reminder when an undisputed invoice passes its due date, while pausing communications if a return, pricing discrepancy, or delivery claim is open.
Keep human review where context affects the decision. Relevant cases include strategic customer accounts, partial payments with unclear deductions, changes to bank details, refunds, credit-limit overrides, write-offs, and unusual credit notes. Over-automation can create confident but incorrect actions, including chasing customers for invoices already paid or escalating balances that are legitimately disputed.
Build integration and data controls before scaling
AR tools depend on information from order management, enterprise resource planning, customer records, banking systems, and sometimes ecommerce or payment platforms. Define the authoritative system for each field: customer identity, billing contact, payment terms, tax treatment, invoice status, dispute status, and cash receipt. If two systems can overwrite the same field without a clear hierarchy, automation may accelerate errors.
Test more than the standard invoice path. Retail-specific scenarios can include returns after invoicing, promotional deductions, consolidated payments, remittances covering multiple locations, short payments, foreign currencies, duplicate customer records, and orders amended after fulfilment. Confirm how each event updates the ledger and what evidence remains for review.
Access controls should reflect segregation of duties. A user who changes customer bank or payment information should not automatically approve the related refund or adjustment. Privileged access, integration credentials, and configuration changes need named owners and periodic review. Logs should show the originating data, automated action, user intervention, timestamp, and final accounting result.
Integration also creates operational dependency. Document what happens if invoice delivery, bank feeds, or the ERP connection fails. Staff need a controlled fallback process, a reconciliation procedure after service restoration, and rules preventing duplicate invoices or reminders.
Design approval, exception, and communication rules
Financial control should be embedded in the workflow. Create an authority matrix for credit notes, refunds, write-offs, payment-plan changes, collection escalation, and account holds. Thresholds alone are insufficient: rules should also consider transaction type, customer risk, related open disputes, and whether bank details recently changed.
Every exception needs an owner, service expectation, escalation route, and resolution code. Useful queues might cover unmatched receipts, disputed invoices, failed delivery, broken payment promises, and data-sync failures. Avoid a single generic exception inbox, which recreates the opacity that automation was meant to remove.
Customer communications deserve the same governance as ledger entries. Review reminder language, timing, channel, and escalation by customer segment. Messages should identify the invoice and offer a clear route to report a dispute or provide remittance information. Finance staff must be able to pause inappropriate sequences, with the reason recorded. Otherwise, automated collections can damage commercially important relationships.
Role changes should be explicit. Automation may reduce invoice preparation, status checking, and routine follow-up, but staff will spend more time maintaining customer data, resolving exceptions, reviewing proposed matches, analysing overdue balances, and monitoring controls. Training should cover both system operation and the circumstances requiring intervention.
Roll out in controlled stages
Begin with a bounded segment, such as one customer group, entity, or low-complexity invoice stream. Run the automated and existing processes in parallel long enough to compare invoice totals, delivery status, cash allocation, aging, and general-ledger balances. Define acceptance criteria before launch rather than declaring success because the system is live.
A sensible sequence is to establish clean master data and reliable invoice delivery first, then add reminders, payment visibility, matching assistance, and more advanced collection workflows. Automating unstable data or inconsistent policies simply makes the resulting mistakes faster and harder to trace.
During the pilot, review exceptions frequently. A high exception rate may indicate poor configuration, but an implausibly low rate can mean the rules are silently accepting questionable transactions. Sample both automated successes and rejected items. Finance, IT, internal control, customer service, and commercial account owners should all participate in the review.
Measure control and cash outcomes together
Measure the baseline before implementation and compare like-for-like customer populations. Track staff hours spent on invoice preparation, reminder administration, payment-status investigation, matching, and dispute handling. Monitor invoice-delivery failures, unmatched cash, exception volumes, resolution time, manual overrides, and reconciliation differences.
For collection performance, use aging by customer segment, the proportion of invoices paid by due date, overdue balances, dispute duration, and forecast accuracy. Days sales outstanding may help, but it can move because of sales mix, seasonality, payment terms, or a few large accounts. It should not be attributed to automation without investigating those factors.
Also assess customer effects: duplicate reminders, complaints about collection messages, portal or payment failures, and time required to resolve disputes. Review control indicators such as unauthorised configuration changes, approval breaches, stale user access, and unresolved integration failures.
The decision should account for subscription and implementation costs, data preparation, integration maintenance, training, control testing, and vendor dependency. Peak Design’s sponsored case can help finance teams ask where manual AR work is consuming capacity, but it cannot substitute for an independent business case. A responsible rollout automates repeatable work, keeps judgment around consequential exceptions, and proves through reconciliations and measured outcomes that efficiency has not displaced financial control.