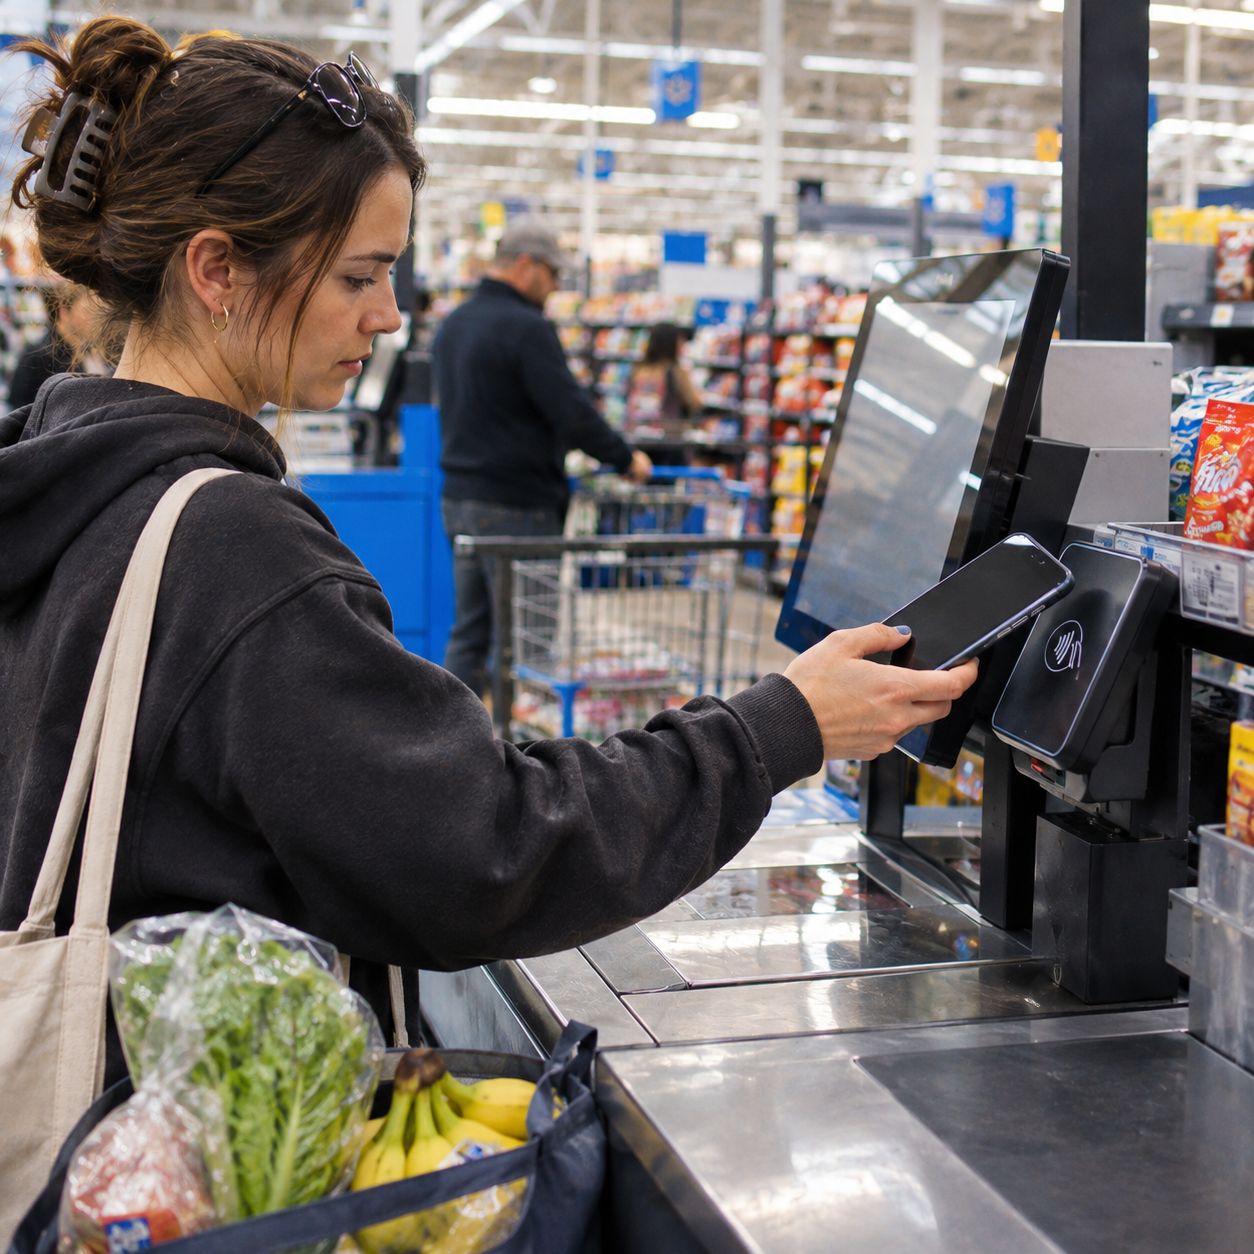
Walmart’s decision to accept Apple Pay and Google Pay is more than an added checkout feature. As reported by Retail Dive, the retailer is introducing the digital wallets through a phased rollout across Walmart and Sam’s Club locations. For retail operators, the important lesson is not simply that mobile wallets have gained another major merchant. It is that payment-method changes should be treated as operational rollouts involving customer behavior, checkout technology, employees and exception management.
A wallet may make payment easier for some shoppers, but enabling it successfully requires more than switching on a terminal setting. Retailers must determine whether demand justifies the change, identify dependencies across their payment stack, test real store conditions and decide how success will be measured. Walmart’s phased approach provides a useful case study for structuring that work without assuming that every merchant has the same systems, customers or rollout capacity.
What changed—and why the rollout sequence matters
Retail Dive reports that Walmart is adding support for Apple Pay and Google Pay, extending customers’ payment choices beyond the retailer’s existing options. The significance lies partly in Walmart’s scale and partly in its rollout method: introducing a payment method across Walmart and Sam’s Club is an implementation programme, not a single technical event.
A phased release allows a retailer to learn before exposing the entire estate to a new checkout process. Store environments differ in terminal models, software versions, network performance, lane formats and employee familiarity. Clubs may also have different checkout journeys from conventional stores. Treating all locations as identical could hide failures until they affect large numbers of transactions.
Other retailers should not copy Walmart’s sequence mechanically. They should copy the principle: separate technical enablement from controlled validation and broad deployment. The right rollout unit might be a region, store format, terminal type or checkout channel. The objective is to contain risk while gathering evidence from representative operating conditions.
Start with payment demand, not competitor pressure
A prominent retailer’s adoption can increase customer expectations, but it does not establish the business case for every merchant. Operators should first identify whether shoppers are attempting or requesting wallet payments. Evidence can come from checkout feedback, customer-service records, abandoned transactions, employee observations and payment-preference research. Staff reports need structure: “customers ask for it” is less useful than recording where, when and how often requests occur.
Demand should also be assessed by journey. A wallet may be especially relevant at high-throughput lanes, self-checkout or locations serving customers accustomed to contactless payment. Conversely, a retailer whose customers predominantly use cash or store-specific tender may rank the change differently. The decision is about reducing a documented payment obstacle, not merely matching a headline.
Retailers should clarify which customer problem they expect to solve. Possible goals include broadening tender choice, reducing confusion among customers who present phones at contactless terminals or improving consistency between stores. These are hypotheses to test rather than guaranteed outcomes. Without an explicit goal, a rollout can be technically successful yet impossible to evaluate.
Map the entire payment path before enabling wallets
Apple Pay and Google Pay sit at the customer-facing edge of a larger system. Acceptance depends on the interaction among the device, terminal, point-of-sale application, payment processor, acquiring arrangements, card networks and the retailer’s transaction rules. A contactless-capable terminal does not by itself prove that every wallet transaction and checkout scenario will work correctly.
Before piloting, operators should inventory terminal hardware and firmware by location, point-of-sale software versions, processor support and configuration differences among store formats. They should test whether wallet transactions are categorized, authorized and reconciled correctly. Receipts, refunds, partial reversals, voids and disputed payments deserve the same attention as an ordinary purchase.
Loyalty and store-payment features can complicate the journey. Teams should document whether customers must present loyalty credentials separately, whether promotions apply as expected and how cashiers identify the transaction when the physical card number is not shown. Online, app and in-store payment experiences should not be assumed to behave identically.
Responsibility must also be explicit. Retail technology, payments, finance, store operations, customer support and fraud teams each own different failure points. A dependency map should identify who can change configurations, who approves deployment and who has authority to pause it.
Design a pilot that tests stores, not just terminals
A useful pilot includes enough variation to reveal operational weaknesses. Retailers can select stores representing different terminal generations, transaction volumes, network conditions and checkout formats. If self-checkout and staffed lanes use different software or procedures, both need coverage. A technically convenient test store alone may produce misleading confidence.
Test scripts should cover routine purchases and foreseeable exceptions. These include a declined authorization, a customer tapping the wrong device, repeated taps, a transaction that appears incomplete, a refund without the physical card and a terminal that stops accepting contactless payments. Teams should confirm what the customer sees, what the employee sees and what appears in back-office reporting.
Define escalation paths before launch. Frontline employees need to know when to retry, offer another tender, move the customer to another lane or contact support. Support teams need diagnostic information such as store, lane, terminal, time and transaction status. A pilot cannot generate useful learning if incidents are captured only as informal complaints.
Deployment gates keep the expansion evidence-based. A retailer might require stable authorization behavior, accurate reconciliation, acceptable incident levels and completed employee preparation before proceeding to the next group. These gates need not rely on invented industry benchmarks; each operator can establish thresholds based on its current payment performance and risk tolerance.
Prepare employees for the questions customers will ask
Training should be short enough for store use but specific enough to prevent improvisation. Employees need to know which wallets are accepted, where customers should hold their device, what a successful payment looks like and what to do if the terminal or phone does not respond. They should avoid making promises about a customer’s bank, device settings or wallet eligibility.
Exception handling is particularly important because customers may interpret a failed wallet attempt as retailer rejection, even when the issuer declined the transaction or the device was not authenticated. A simple troubleshooting flow can distinguish among retrying the tap, asking the customer to authenticate, checking terminal status and requesting another payment method.
Signage and interface language should match actual availability. Advertising acceptance before all relevant lanes or stores are enabled creates friction rather than removing it. During a phased rollout, store-level communication should accurately reflect where the option works, while customer-service teams should have access to the current deployment status.
Measure whether the new method improves checkout
Adoption rate is useful, but it is not a complete verdict. Retailers should compare wallet usage by store, lane type and rollout stage while monitoring authorization outcomes, contactless errors, support contacts, refund problems and reconciliation exceptions. Checkout duration can be reviewed where reliable measurement already exists, but operators should avoid claiming speed improvements without evidence from their own environment.
Qualitative signals matter as well. Are employees encountering fewer questions after training? Do customers understand when to authenticate? Are particular terminal models generating disproportionate incidents? Combining operational records with frontline feedback can reveal whether the problem is technology, communication or process design.
The practical next step is to write a wallet-readiness brief before contacting stores: define the customer need, inventory payment dependencies, choose representative pilot locations, document normal and exception flows, assign incident owners and establish rollout gates. Walmart’s move shows that even a widely recognized payment method benefits from phased implementation. For other retailers, the strategic advantage will not come from adding a logo at checkout; it will come from making the new tender dependable across the complete store journey.