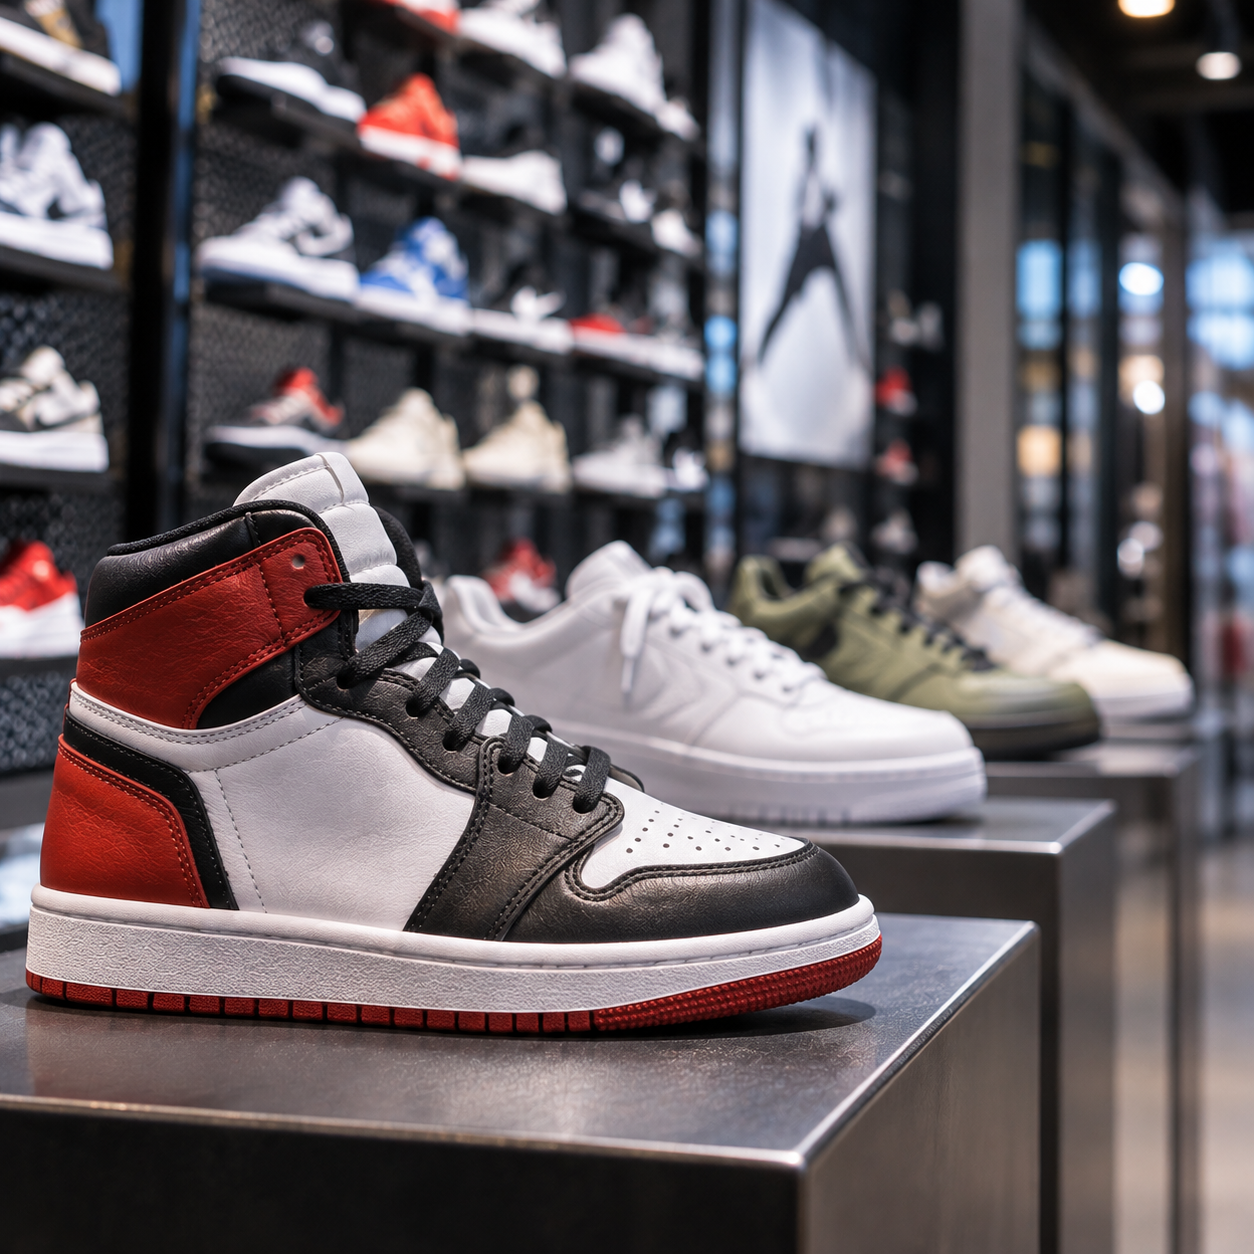
Foot Locker’s reported declines, losses and gloomy outlook offer a warning to specialist retailers whose traffic depends on a steady rhythm of sneaker releases. Retail Dive’s account points to fewer launches and changing athletic-footwear demand as important pressures on the business. The lesson extends beyond footwear: when customers visit primarily for new drops, retro revivals or one narrow product category, a quieter release calendar can weaken traffic before management has time to adjust inventory.
This is not simply a question of whether a particular sneaker remains popular. Launch-dependent retail combines several linked exposures: brands control release schedules, merchants commit to stock before demand is fully visible, and a small number of styles often generate disproportionate excitement. Operators should therefore treat Foot Locker’s slowdown as an inventory and merchandising problem—not just a temporary sales disappointment.
Why fewer launches can hurt more than launch-day sales
A major release does several jobs. It sells the featured shoe, creates urgency, brings customers into stores and digital channels, and generates purchases in adjacent products. When release activity declines, a retailer can lose both direct launch revenue and the wider traffic halo.
That effect is particularly damaging when the core assortment contains many products that customers regard as substitutes they can buy elsewhere. Without a sought-after launch, shoppers have less reason to choose a specialist over a brand’s own channel, a marketplace or a general sporting-goods retailer. Lower traffic then reduces opportunities to sell apparel, accessories and everyday footwear.
Shifting demand adds another complication. A retailer may have ample stock while still lacking the silhouettes, uses or price points gaining relevance. Retro styles can sustain demand for long periods, but dependence on a retro cycle creates risk when consumers move toward different footwear aesthetics or occasions. Inventory purchased under yesterday’s trend assumptions can become a markdown burden even if the broader footwear market remains active.
The reported Foot Locker performance illustrates this combined problem: reduced launch activity limits traffic catalysts while changing athletic-footwear preferences challenge the productivity of the existing assortment. Specialist operators should not assume that the next major release will automatically repair both issues.
Measure dependence on the release calendar
The first step is to map how much of the business relies on launches, including revenue that appears unrelated to them. Examine sales and visits during launch weeks against ordinary weeks, separating the featured product from attachment purchases. If apparel and accessories also fall sharply when launches are scarce, their demand may be less independent than category reporting suggests.
Operators should evaluate concentration through several lenses:
- Calendar concentration: How much seasonal performance depends on a few release dates?
- Style concentration: How much demand rests on retro franchises, limited editions or one silhouette family?
- Brand concentration: Which suppliers account for the products that generate visits, full-price sales and repeat engagement?
- Customer concentration: Are the most active buyers interested only in drops, or do they purchase across everyday categories?
- Channel concentration: Does excitement translate across stores and e-commerce, or is one channel dependent on launch allocation?
These questions should be answered with contribution and inventory data, not revenue alone. A launch can produce high sales but weak economics after fulfilment complexity, customer-acquisition spending or low-margin attachment items. Conversely, an everyday category may attract less attention while producing steadier full-price sell-through.
Build scenarios for a normal calendar, a delayed calendar and a season with materially fewer releases. The objective is not to predict each drop. It is to identify how quickly traffic, stock turns and markdown exposure deteriorate when the launch engine slows.
Separate supplier importance from supplier vulnerability
Specialists need influential brands, but reliance becomes dangerous when a supplier controls both customer excitement and stock access. Retailers may have limited influence over launch timing, allocations, direct-to-consumer availability or the mix of products offered around a release. A desirable partnership can therefore remain a material operating risk.
Create a supplier exposure map showing each brand’s share of sales, inventory commitments, launch-generated traffic and markdowns. Add qualitative factors: cancellation rights, order flexibility, replenishment speed, exclusivity, lead times and the supplier’s own distribution strategy. This reveals whether a brand is valuable because it creates profitable demand or merely unavoidable because the retailer has not developed alternatives.
Diversification should not mean filling shelves with unfamiliar labels without proven demand. Test emerging brands, performance niches and alternative price tiers through smaller orders, selected stores or online-first releases. Set evidence thresholds for expansion, such as repeat demand, full-price sell-through and cross-category attachment. Controlled tests reduce dependence without exchanging one concentration problem for excess stock.
Use demand signals before making deep commitments
Historical sales can mislead when the release cadence or fashion cycle changes. A retro model that sold strongly during scarcity may perform differently when repeated versions saturate the market. Merchants need signals that distinguish durable demand from launch excitement.
Useful indicators include product-page engagement, wish lists, search behaviour, reservation interest, size-level selling patterns, cancellations and the speed at which demand broadens beyond enthusiasts. Store teams can add evidence about requested styles, intended uses and objections to price or design. Monitor these signals by product family rather than treating “sneakers” as a single demand pool.
Translate the evidence into staged commitments. Keep initial buys conservative where trend durability is uncertain, negotiate replenishment where possible and define review points before accepting follow-on stock. For retro products, compare each new colourway or reissue with the franchise’s recent trajectory—not only its historical peak.
Markdown triggers should also be established before merchandise arrives. Warning signs can include weak early full-price selling, poor size balance, declining search interest or heavy competitive availability. Predetermined actions—cancel, transfer, bundle, reduce replenishment or mark down selectively—help prevent optimism from turning slow stock into aged stock.
Build complementary categories that can stand alone
Adding categories only improves resilience if they have an independent reason to buy. Generic accessories placed beside a launch may raise basket size, but they will not replace traffic when launches disappear. Complementary categories should address the same customer’s broader needs while operating on different demand cycles.
A footwear specialist might assess everyday basics, care products, socks, performance apparel or footwear for distinct occasions. The correct choices depend on customer evidence and brand position. Each category should be evaluated for repeat rate, margin after markdowns, inventory depth, attachment without launches and its ability to generate visits independently.
Avoid expanding so widely that specialist authority disappears. The goal is a portfolio of related demand engines: launches for excitement, replenishable products for continuity, and selected adjacent categories for repeat purchasing. Clear space and inventory limits prevent diversification from becoming uncontrolled assortment growth.
Actions for the next buying cycle
- Quantify sales, traffic and attachment dependence on the largest release weeks.
- Stress-test the plan against delayed launches, fewer launches and weaker retro demand.
- Rank supplier exposure using inventory flexibility and markdown history as well as sales.
- Reduce initial commitments where demand depends mainly on past franchise success.
- Set product-level review dates and markdown triggers before stock arrives.
- Test complementary categories for standalone demand rather than launch-day attachment alone.
Foot Locker’s reported difficulties show why launch scarcity and changing footwear tastes cannot be managed solely through promotion. Retailers need to know which demand is owned by their proposition and which is borrowed from a supplier’s calendar. Those that make that distinction can protect cash, respond earlier to shifting styles and remain relevant when the next headline release is farther away than expected.