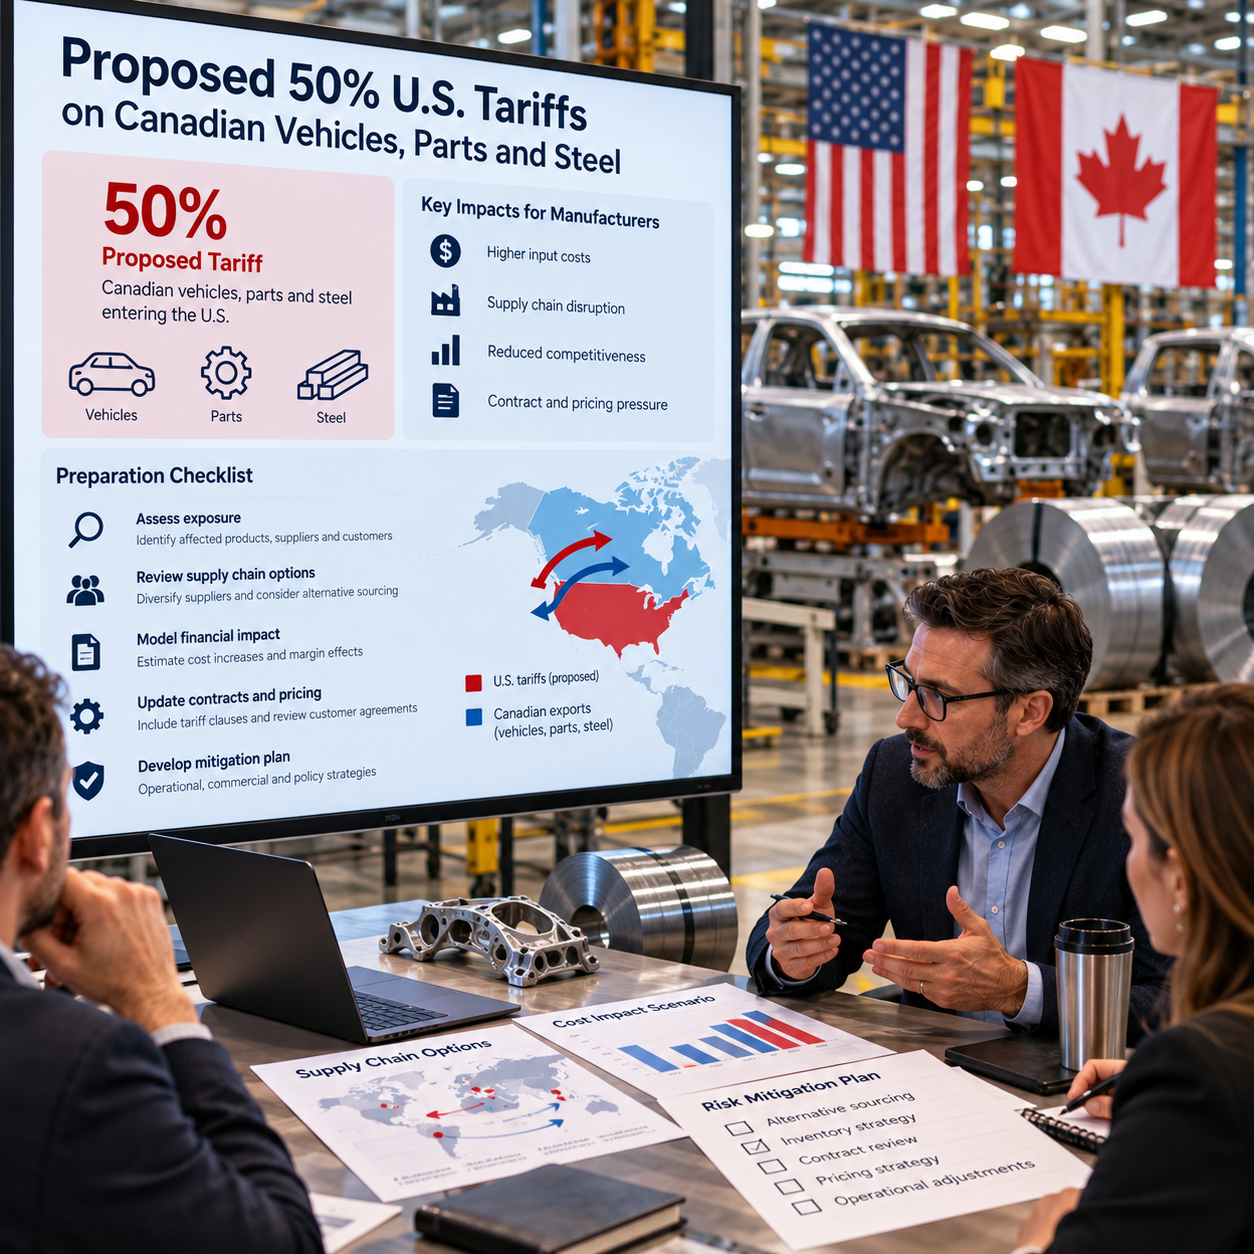
A reported U.S. tariff announcement targeting Canadian cars, trucks, automotive parts and steel creates an immediate planning problem for manufacturers, importers and distributors—even though an announcement is not the same as implemented policy. Supply Chain Dive reports that the proposed 50% tariffs are intended to begin Jan. 1. Businesses should therefore prepare for possible cost disruption without treating the proposed rate, scope or effective date as settled customs law.
The practical objective is not to predict the trade dispute. It is to identify where exposure sits, determine who would bear the charge, and prepare actions that remain commercially sensible across multiple outcomes. The following framework combines the reported announcement with an operator-focused contingency plan.
Find direct and embedded Canadian exposure
Begin with transaction-level data rather than a list of Canadian suppliers. Direct exposure may include finished vehicles, replacement parts, components, steel coils, sheet, bar or fabricated products imported from Canada. Indirect exposure can be harder to see: a U.S. supplier may use Canadian steel, or a non-Canadian assembly may contain Canadian automotive components.
Extract at least 12 months of purchase and import records, then map each relevant item to its supplier, manufacturer, declared country of origin, Harmonized Tariff Schedule classification, customs value, annual volume and destination facility. Link this information to bills of materials so procurement teams can identify products whose costs could rise through embedded inputs even when the company is not the importer of record.
Segment exposure into three categories:
- Direct customs exposure: the business imports potentially covered Canadian-origin merchandise.
- Contractual pass-through exposure: a supplier or distributor imports it and may seek to pass on tariffs.
- Market exposure: domestic or third-country suppliers may increase prices if Canadian supply becomes more expensive or scarce.
Do not assume that shipment from Canada establishes Canadian origin, or that shipment through another country changes origin. Origin can depend on applicable rules and the production performed. Flag uncertain records for review rather than assigning them based on supplier address.
Validate classifications before estimating the bill
The phrase “vehicles, parts and steel” is not sufficiently precise for budgeting. Actual liability would depend on the legal instrument, covered tariff lines, exclusions, origin rules, valuation rules and effective-date provisions if the proposal is implemented.
For every material item, compare the current tariff classification with product specifications, composition, dimensions, function and manufacturing process. Generic descriptions such as “automotive component” or “steel part” are inadequate. A customs broker or trade adviser should examine high-value and high-volume lines, prior rulings, and any classifications that have changed across entries or suppliers.
Also confirm which entity is importer of record and what value is declared. Finance should not simply apply 50% to total Canadian procurement. A preliminary exposure model can use that rate as an announced-policy scenario, but it should apply only to items provisionally identified as potentially covered and should remain clearly labelled as an estimate—not a forecast of final duty liability.
Create an evidence file containing classifications, origin support, supplier certifications, entry documents and the reasoning behind material decisions. If policy language is later published or revised, this record will allow the team to re-screen goods quickly.
Determine who is contractually responsible
Commercial responsibility may not follow the purchasing team’s assumptions. Review Incoterms, purchase orders, master supply agreements, price-adjustment clauses and customer contracts. Incoterms help allocate transport tasks, costs and import formalities, but they do not by themselves resolve every pricing or tariff dispute.
For each affected relationship, answer four questions: Who is importer of record? Who initially pays duties? Can that party pass the cost through? Can either party reprice, suspend, terminate or renegotiate after a tariff change?
Pay particular attention to clauses covering changes in law, taxes and duties, force majeure, hardship, material adverse change, fixed-price periods and notice requirements. Sales teams must perform the same review downstream. A manufacturer might owe a new import charge immediately while being locked into customer pricing for months.
Avoid unilateral assumptions. Ask suppliers to document their origin assessment, likely pass-through approach, available substitutes and notification timetable. Record agreements in contract amendments rather than relying on informal assurances.
Model landed cost, cash flow and margin consequences
Build scenarios rather than one tariff budget. At minimum, model no implementation, implementation broadly consistent with the announcement, and a narrower or delayed measure. These are planning cases, not predictions.
For each potentially affected stock-keeping unit, calculate the change in landed cost and then follow it through the business. Include possible effects on duty outlays, broker fees, freight, carrying costs, supplier prices, working capital and customer margin. Avoid double-counting: a supplier’s tariff-inclusive price increase and a direct duty estimate should not both be applied to the same import.
Rank products by gross-margin impact, absolute cash requirement, customer importance and substitutability. The largest duty amount may not be the most urgent risk. A low-margin component with no approved alternative can be more dangerous than an expensive input used in a product with pricing flexibility.
Finance should also test timing. Duties may create a cash requirement before higher selling prices can be negotiated or collected. Establish approval thresholds for repricing, temporary surcharges, minimum-order changes or stopping sales of structurally unprofitable products.
Use inventory and sourcing selectively
Accelerating imports before Jan. 1 may look attractive, but it is not automatically prudent. Before ordering early, assess shelf life, storage capacity, financing cost, demand certainty, cancellation rights and the risk that final policy differs from the announcement. Customs counsel should confirm how any implemented measure would treat goods in transit, entered for consumption or withdrawn from a bonded facility around the effective date.
Prioritize inventory only where exposure is credible, demand is firm and the carrying risk is acceptable. Avoid broad stockpiling based solely on a headline rate.
In parallel, request qualified alternatives from suppliers in the United States and other countries. Compare total landed cost, not quotation price alone. Include tooling, testing, engineering approval, quality audits, minimum quantities, lead times and origin. Automotive and safety-critical parts may require lengthy customer or regulatory validation, while steel substitutions can affect grade, tolerances, performance and downstream processing.
Retaliation is another planning risk. Canadian countermeasures could affect exports, cross-border production flows or inputs outside the initially announced U.S. categories. Firms operating in both markets should map outbound as well as inbound exposure without assuming what retaliatory measures will be adopted.
Set a readiness process for policy changes
Assign one cross-functional owner and maintain a live exposure register. Procurement should manage supplier alternatives; customs specialists should verify classification and origin; legal teams should interpret contracts; operations should assess inventory and qualification constraints; finance should own margin and cash scenarios; sales should handle customer communications.
Before the announced Jan. 1 date, operators should complete these actions:
- List direct imports and embedded Canadian automotive and steel inputs.
- Verify classifications, origin support, customs value and importer-of-record status.
- Review Incoterms and tariff, repricing and termination clauses on both purchasing and sales contracts.
- Model product-level landed cost, cash needs and gross-margin effects under multiple scenarios.
- Seek documented supplier plans and quotes for realistic alternatives.
- Approve early inventory only against explicit demand and carrying-risk tests.
- Designate trusted sources for monitoring official policy text, effective dates, exclusions and Canadian responses.
The key distinction should remain visible in every internal briefing: the source reports an announced intention for 50% tariffs beginning Jan. 1, not proof that those tariffs have already taken effect. Good preparation preserves options while avoiding irreversible decisions based on policy that may change before implementation.